
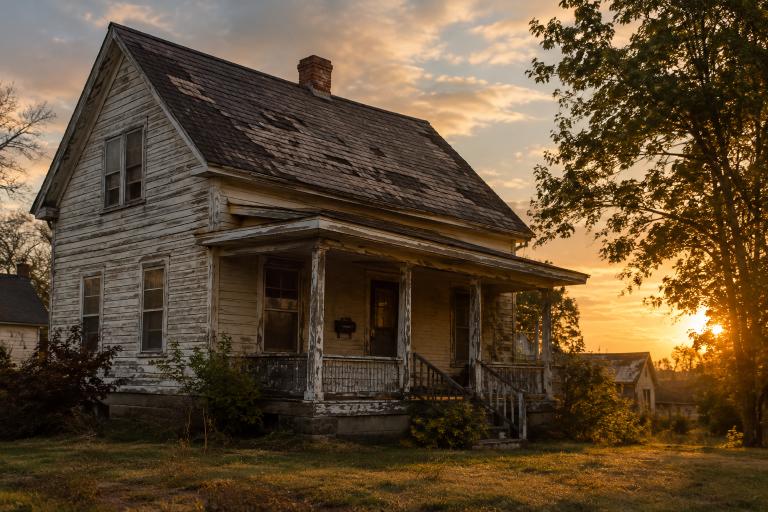
Selling a house as-is means offering the property in its present condition, without promising to make repairs before closing. Homeowners considering a direct-sale route may see companies that we buy houses as a marketing message, but the important question is whether the written offer, timeline, and expected net proceeds fit the seller’s situation.
An as-is sale can be practical for an inherited property, a vacant home, or a house with deferred maintenance. It is not, however, a shortcut around inspections, negotiations, disclosures, title work, or a carefully written purchase agreement.
What Selling a House As-Is Really Means
In an as-is transaction, the seller generally tells the buyer that the home will be transferred in its current condition. The buyer may still inspect the property, request a price reduction or a credit, or cancel if the contract allows. The contract controls the inspection period, repair requests, contingencies, deposit rules, and closing date.
For example, a seller may list an older home with a worn roof and outdated electrical panel as-is. The seller is not agreeing to replace either item, but a buyer can still evaluate those conditions and decide whether the price reflects the work needed.
Why Homeowners Choose an As-Is Sale
Many sellers choose this approach because preparing for a traditional listing can require money, time, and coordination. Common reasons include:
- An inherited or probate property that the family does not plan to keep.
- Major repairs that exceed the owner’s available budget.
- A relocation, divorce, financial pressure, or another firm deadline.
- A vacant property with continuing mortgage, tax, insurance, utility, or maintenance costs.
- A rental home with deferred maintenance and a seller who does not want to manage renovations, staging, or showings.
How Condition Can Affect an As-Is Offer
A property in need of repairs may attract fewer owner-occupant buyers, particularly when defects could complicate financing or insurance. Buyers also tend to account for repair costs, uncertainty, and the time required to complete the work. The resulting discount varies substantially based on local demand, the home’s location, the seriousness of the issues, and whether the likely buyer is an owner-occupant or investor.
Repairs Worth Reviewing First
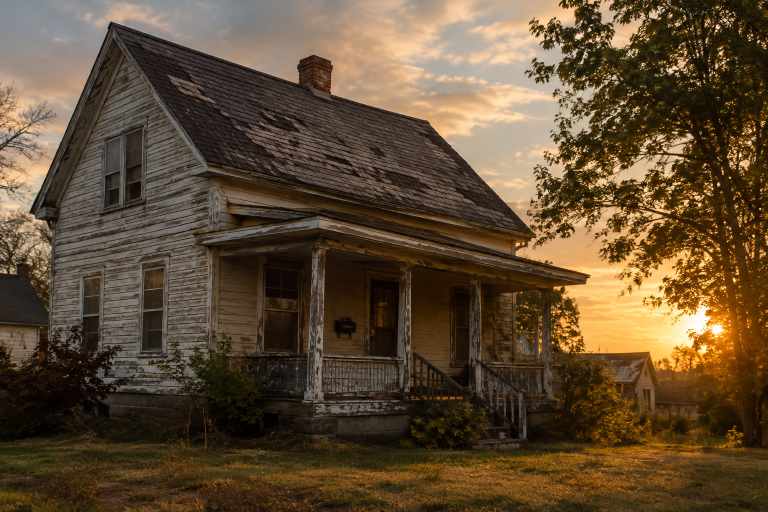
Before deciding not to repair anything, get written estimates for issues that affect safety or basic function. These may include active roof leaks, water intrusion, drainage failures, electrical hazards, heating or cooling failures, structural movement, plumbing leaks, and missing smoke or carbon monoxide detectors. Cosmetic work, such as paint or landscaping, may improve presentation, but an expensive remodel does not automatically produce a matching increase in sale price.
Compare the Main Selling Paths
- Traditional listing: May provide broader exposure and a higher gross price, but often requires preparation, showings, buyer financing, and more time.
- As-is listing: Lets the seller market the home without committing to repairs, but buyers may make lower offers or seek credits after inspection.
- Direct cash sale: May close faster and avoid a loan-approval contingency, but the offer may be lower, and the contract must be reviewed closely.
- For-sale-by-owner: Gives the seller more direct control, but also places marketing, screening, paperwork, negotiation, and disclosure management on the seller.
How to Compare a Cash Offer
The advertised price is only one part of an offer. Request the complete agreement in writing, ask for proof of funds, and confirm whether the buyer may assign the contract to someone else. Review when the price becomes final, what inspection or cancellation rights exist, who pays particular closing costs, and whether any fee can be added later.
Also ask for an itemized estimate of your proceeds. Closing expenses can vary by contract and location, and a bottom-line total for title and closing services is more useful than relying on a vague statement that a buyer will cover all costs.
Net Proceeds Matter More Than Sale Price
Compare each path using the same simple calculation: expected sale price, minus mortgage payoff, repairs and cleanup, agent compensation if applicable, buyer credits, title and closing charges, and holding costs through closing. Holding costs can include mortgage payments, property taxes, insurance, utilities, lawn care, storage, and temporary housing.
A lower cash offer can sometimes yield a comparable result if it eliminates major repairs, several months of expenses, and the risk that a financed buyer fails to close. Conversely, a higher offer may be stronger if the home needs little work and the seller has time to market it properly.
Disclosure Duties Still Apply
As-is wording does not permit a seller to hide known material problems. Sellers should accurately address known roof, foundation, water, plumbing, electrical, mold, fire, storm, flooding, permit, or code concerns when applicable under local law. Requirements differ by state, so a real estate attorney or qualified local professional can help when the seller is uncertain.
Federal rules also apply to most pre-1978 housing. Sellers of covered homes must disclose known lead-based paint and related hazards before a buyer signs, as explained in the EPA’s real estate disclosure requirements for lead hazards.
Warning Signs in a Cash Home Offer
- Pressure to sign immediately or avoid reading the agreement.
- Promises made verbally but omitted from the contract.
- Missing proof of funds or an unclear buyer identity.
- Broad cancellation rights, open-ended inspection terms, or repeated price-reduction language.
- Unexplained assignment clauses, surprise fees, or a closing date without clear obligations.
A Practical Selling Plan
- Decide whether speed, price, convenience, or certainty is the top priority.
- Gather mortgage details, tax information, permits, repair invoices, and insurance records.
- Review recent comparable sales and obtain estimates for major repairs.
- Compare at least two realistic selling options using net proceeds, not headlines.
- Read every deadline, contingency, fee, inspection term, and cancellation provision before signing.
- Use a neutral title company, escrow professional, or real estate attorney to help manage closing and payoff paperwork.
Common Questions About Selling a House As-Is
Can a buyer inspect an as-is home?
Yes. An as-is sale can include an inspection. The purchase agreement determines what the buyer may do after receiving the inspection results.
Does selling as-is always mean less money?
Not always. A lower sale price may be partially offset by reduced repair costs, lower carrying costs, and a faster or simpler transaction.
Should a seller accept the first offer?
Comparing more than one written offer can reveal differences in fees, contingencies, timing, and actual proceeds. The right choice depends on the seller’s priorities and the buyer’s reliability.
Choose the Path That Fits the Situation
Selling as-is can make sense when repairs are expensive, the home is vacant, or the seller needs a straightforward closing. A traditional sale may be better for a home in good condition when the seller can wait for broader market exposure. In either case, clear disclosures, written terms, buyer verification, and a realistic net proceeds calculation support a safer decision.